Investing for Professionals By Chanakya Capital
Doctors, lawyers, chartered accountants, senior executives and founders tend to share one problem: strong earnings, very little time. Wealth builds quickly, but the attention needed to manage it well rarely keeps up. Chanakya Capital works with professionals through concentrated, research-led PMS and AIF strategies, so the investing gets the full-time focus your career doesn’t leave room for.
Earning well but short on time to manage it?
Get in touch with Chanakya Capital’s fund management team.
The Professional’s Investing Problem
Most professionals run into the same few obstacles, whatever the field:
Time:
Researching businesses properly is a second job, and a demanding practice or role leaves little room for it.
Concentration in your own career:
Employer stock, ESOPs or a stake in your own practice already ties wealth to one outcome.
Lumpy income:
Bonuses, partnership payouts and ESOP vests arrive in large, irregular amounts that are easy to park and forget.
Tax drag:
Higher income brackets make after-tax returns, not headline returns, the number that matters.
How Chanakya Capital Works With Professionals
A Manager Doing the Research:
Through PMS, a dedicated team builds a portfolio of 15–25 high-conviction stocks, held directly in your own demat account. Our Portfolio Management Services explains how that portfolio is built and monitored.
Direct Access Without Daily Involvement:
You speak with the people actually managing your capital, not a relationship manager relaying updates. Decisions stay with the manager; you stay informed.
Reporting You Can Review in Minutes:
Where Professional Capital Usually Comes From
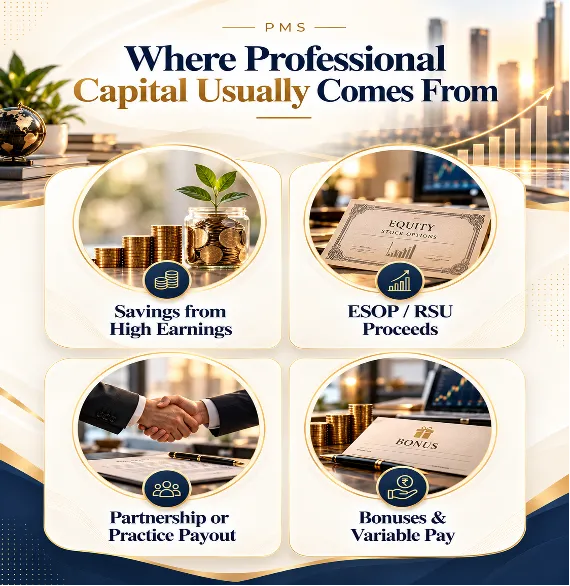
Investable surplus rarely arrives in a single neat sum. Common sources include:
Accumulated savings from several years of high earnings
ESOP or RSU proceeds after a vest or liquidity event
A partnership payout or the sale of a share in a practice
Annual bonuses and variable pay set aside over time
Existing shares can sometimes be transferred in rather than sold, depending on whether they fit the strategy.
Is PMS Right for You Yet?
Not every professional is at that stage, and it’s better to say so plainly. PMS needs a SEBI-mandated minimum, and it suits a multi-year horizon and comfort with concentrated equity risk. Our guide to the minimum investment for PMS explains how the ₹50 lakh threshold works and how it can be funded. Because gains are taxed as direct equity, it’s also worth understanding how PMS is taxed before you commit, particularly if you’re in a higher bracket.
Due Diligence for Busy Investors
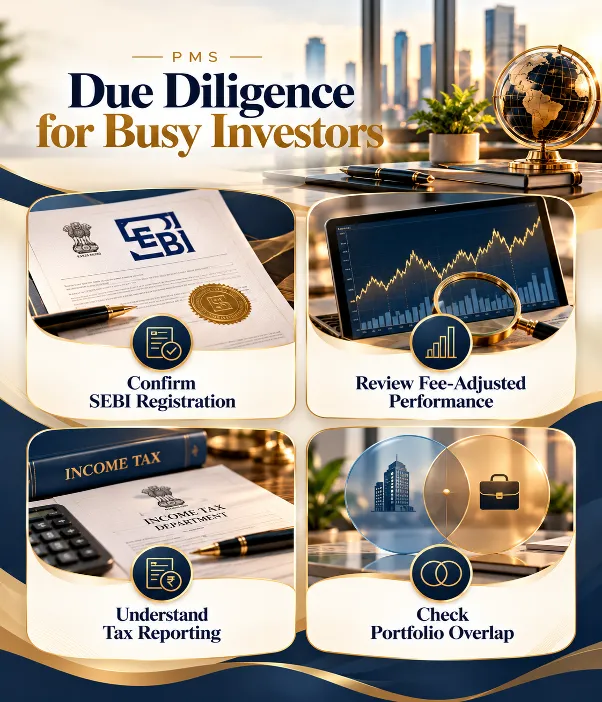
Limited time makes verification more important, not less. Before investing with any manager:
Confirm SEBI registration independently, using SEBI’s investor guidance as your reference
Ask for fee-adjusted performance across a full market cycle
Understand how gains will be reported for the Income Tax Department
Check how much your existing employer or practice exposure already overlaps with the portfolio
Getting Started
01
Take stock of your investable surplus and liquidity needs.
02
Confirm you meet the applicable minimum.
03
Review the strategy, fees and SEBI registration with the team.
04
Complete KYC and documentation.
05
Fund the account and let capital be deployed gradually.
FAQ
Frequently Asked Questions
1. Is managed, concentrated investing suitable for working professionals globally?
Yes. Doctors, lawyers and technology executives in the US, UK and Singapore commonly use separately managed accounts once their savings reach a manager’s threshold, precisely because they lack time to research stocks themselves. PMS is India’s equivalent: direct ownership, full transparency and a portfolio built around your goals rather than a standard basket.
2. How can a professional with ESOP or bonus income invest through PMS?
Large, irregular sums suit PMS well because managers deploy capital gradually rather than all at once, which reduces the risk of entering at a single price. Where appropriate, existing shares can be transferred instead of sold, though holdings outside the strategy are usually liquidated and reinvested.
3. How much time does a PMS investment take to monitor?
Far less than self-directed investing. The manager makes the decisions, and you review regular statements and speak with the fund management team when you choose to. Most professionals find a short monthly or quarterly review is enough.
4. Does a PMS add to concentration risk if I already hold employer stock?
It can, which is why overlap deserves a direct conversation. A concentrated 15–25 stock portfolio carries more weight per position than a diversified fund, so investors with large employer or practice exposure should weigh how the two combine before allocating.
5. Can professionals working abroad invest with Chanakya Capital?
Yes. Non-Resident Indians can invest through NRE or NRO accounts, and overseas investors can use a GIFT City-approved, USD-denominated structure, which works much like an offshore feeder used to access other emerging markets, with simplified repatriation.
References
- SEBI Investor Guidance — Portfolio Management Services: https://investor.sebi.gov.in/pms_final.html
- Income Tax Department, Government of India: https://www.incometax.gov.in