NRI Investors By Chanakya Capital
Non-Resident Indians looking to stay invested in Indian equities often face a more complex path than resident investors, different account types, repatriation rules, and tax treatment that aren’t always clearly explained upfront. Chanakya Capital works with NRI investors through both PMS and AIF structures, built on the same concentrated, research-driven philosophy applied to resident portfolios, with the account structuring handled around NRI-specific regulations.
Many NRIs stay invested in India out of familiarity or family ties, but end up in products that weren’t really built with their situation in mind. The right structure should account for where you live, how you’re taxed there, and whether you need the flexibility to move returns back overseas without friction.
Investing from abroad and unsure where to start?
Get in touch with Chanakya Capital’s fund management team.
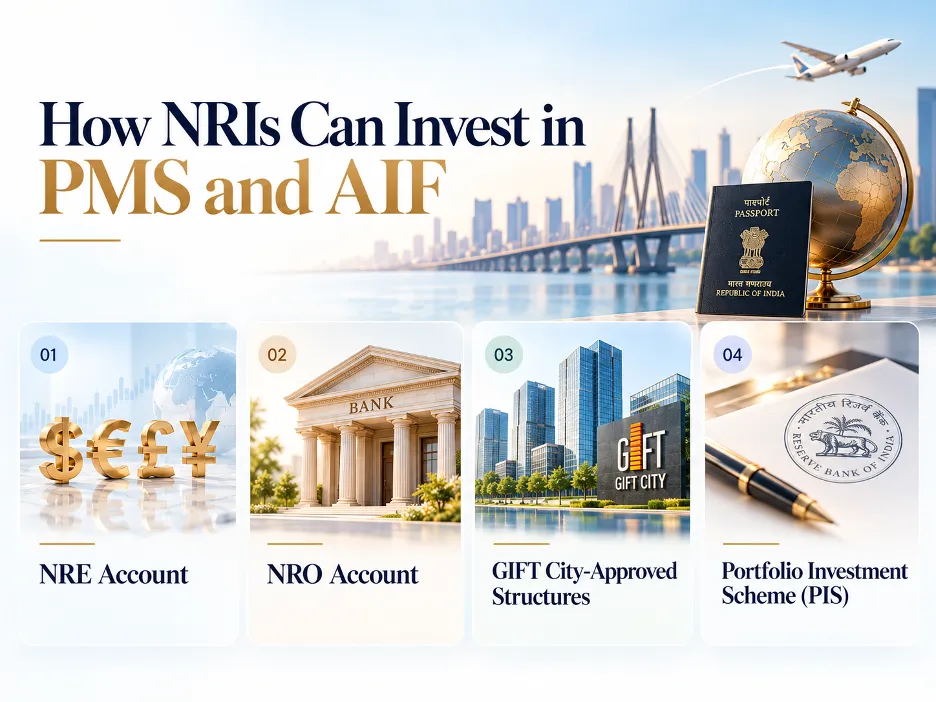
How NRIs Can Invest in PMS and AIF
NRIs can access Chanakya Capital’s strategies through a few routes, depending on their residency status and investment preference:
NRE (Non-Resident External) Account
Funded with foreign earnings, with both principal and returns fully repatriable.
NRO (Non-Resident Ordinary) Account:
Used for India-sourced income, with repatriation subject to specific limits and documentation.
GIFT City-Approved Structures:
USD-denominated access to Indian equities through Chanakya Capital’s offshore gateway, designed for simplified taxation and repatriation.
Portfolio Investment Scheme (PIS)
A separate RBI-regulated route some NRIs use specifically for investing in listed Indian securities.
Each route carries different documentation and compliance requirements, which is why most NRI investors benefit from a conversation before choosing one.
What Makes the NRI Process Different
Beyond standard KYC, NRI onboarding typically requires proof of overseas residency, a PIS permission letter (where applicable), and NRE/NRO account linkage before capital can be deployed.
Repatriation Rules How freely returns can be moved back overseas depends on the account type used to fund the investment, a detail worth clarifying before committing capital, not after.
Tax Treatment and DTAA NRIs are subject to TDS on capital gains at source, though many can claim relief under a Double Taxation Avoidance Agreement (DTAA) between India and their country of residence, depending on where they’re based.
Time Zone and Communication Markets move during Indian trading hours, often outside an NRI investor’s local working day, which makes clear, asynchronous reporting and direct manager access more important than it might be for a resident investor checking in daily.
Why NRIs Choose Chanakya Capital
NRIs can access Chanakya Capital’s strategies through a few routes, depending on their residency status and investment preference:
Same investment philosophy as resident portfolios, concentrated, high-conviction positions built on in-depth research. See investment philosophy for more detail.
GIFT City-approved, USD-denominated access, avoiding currency conversion friction on every transaction.
Direct access to the fund management team, rather than a relationship manager relaying updates from overseas.
Getting Started as an NRI Investor
The process broadly follows the same sequence as for resident investors, with NRI-specific documentation layered in:
- Confirm you meet the ₹50 lakh PMS minimum (or the applicable AIF threshold).
2. Choose your funding route — NRE, NRO, PIS, or a GIFT City structure.
3. Complete KYC along with NRI-specific documentation.
4. Review the strategy and fee structure with the fund management team.
5. Fund the account and allow capital to be deployed gradually.
FAQ
Frequently Asked Questions
1. Can non-resident Indians (and other overseas investors) access Indian equity through a managed account?
Yes. Non-resident investors can participate in Indian markets through a managed account (PMS) using approved banking channels, or through USD-denominated structures set up in GIFT City, India’s international financial hub. The standard minimum ticket still applies, so this route suits investors who already have meaningful capital to allocate to India.
2. Can profits be moved back to your country of residence?
Mostly yes, but it depends on which account funded the investment. Money that came in from abroad through a repatriable account can generally go back out freely, along with the gains. Money routed through a local-income account faces annual limits and extra paperwork. So the way you fund the investment on day one decides how easily you can take it home later.
3. How are gains taxed for a non-resident?
India taxes capital gains at source, so tax is deducted before the money reaches you, much like it would be for a resident investor. The good news is that India has tax treaties with many countries to prevent double taxation, so you may be able to claim credit or relief back home. Treaty terms differ by country, so speak to a cross-border tax advisor before you invest.
4. Do you need a special investment account to get started?
Not always. Some routes into listed Indian securities require a dedicated non-resident investment account, while others, such as GIFT City structures, may not. Your onboarding team can tell you which route is simplest for your residency and funding source, so you don’t have to work it out alone.
5. Can overseas investors choose between a managed account and a pooled fund with Chanakya Capital?
Yes. Both are open to non-resident investors, and both follow the same concentrated, research-led philosophy. What changes is the structure and the way reporting is delivered. Pick the one that matches how closely you want to see your holdings and how simple you want your paperwork to be.
References:
Reserve Bank of India — NRI Account and Investment Guidelines: https://www.rbi.org.in
SEBI Investor Guidance — Portfolio Management Services: https://investor.sebi.gov.in/pms_final.html