Family Offices & Corporates By Chanakya Capital
Family offices and corporates manage capital differently from individual investors, multiple entities, layered governance, and a need for reporting that satisfies trustees, boards, or multiple family stakeholders at once. Chanakya Capital works with both through concentrated, research-driven PMS and AIF strategies, structured to fit how family offices and corporate treasuries actually operate, not retrofitted from a retail product.
Managing capital across multiple entities or stakeholders?
Get in touch with Chanakya Capital’s fund management team.
What Family Offices Need From a Manager
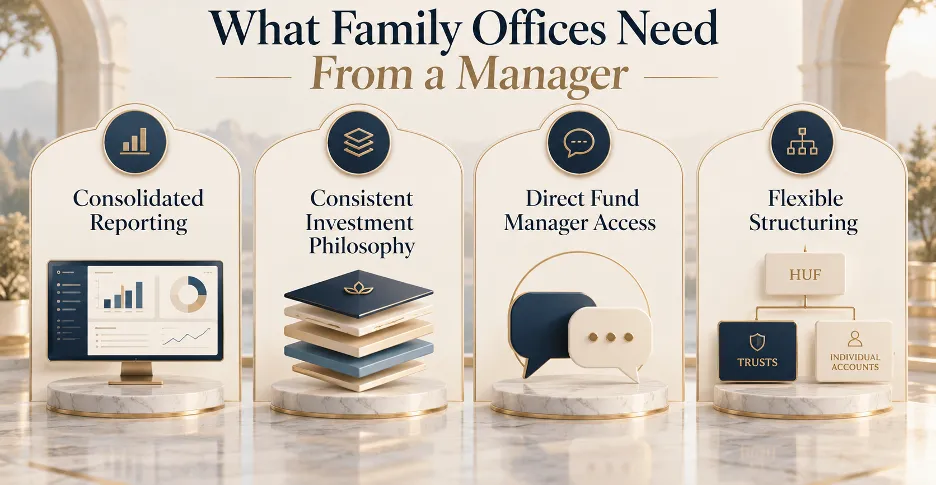
Family offices typically oversee wealth across generations, entities, and sometimes multiple family branches, which changes what matters in a manager relationship:
Consolidated, entity-level reporting that can be shared with trustees or family members without reconstruction.
A consistent investment philosophy applied across accounts held by different family members or trusts.
Direct access to the actual fund manager, not a layer of relationship managers, especially when questions come from the family’s own investment committee.
Flexibility to structure allocations through HUFs, trusts, or individual accounts, depending on the family’s existing setup.
What Corporates Need When Deploying Surplus Capital
Corporate treasuries managing surplus funds have different priorities from both retail and family-office investors:
Transparent, auditable reporting that fits board-level review and statutory compliance requirements.
A manager who understands that corporate capital often has a different risk tolerance and time horizon than personal wealth.
Clear documentation on fees, strategy, and SEBI registration status for internal due diligence and audit trails.
The option to structure the allocation through PMS for direct ownership or AIF for a pooled, simpler reporting format.
PMS or AIF: Which Structure Fits
PMS for Direct Ownership and Customisation Family offices or corporates that want individually managed, directly-owned portfolios with restricted stock lists or entity-specific mandates are typically better served by PMS.
AIF for Simpler, Pooled Reporting Where multiple family members or group entities want exposure to the same strategy without separately managing individual accounts, our Alternative Investment Fund offers a unit-based structure with consolidated reporting.
The Same Philosophy, Either Way Regardless of structure, the underlying approach doesn’t change. Concentrated, high-conviction positions built on in-depth research, apply consistently whether the capital sits with a family trust or a corporate treasury.
Governance and Due Diligence Considerations
Family offices and corporates typically run more formal due diligence than individual investors, often involving an investment committee or board. This usually means verifying SEBI registration independently, reviewing fee structures in writing, and understanding how reporting will flow to multiple stakeholders rather than a single account holder. Investors with sizable allocations may also want to review how this compares with our dedicated page for HNI investors, since many of the same due-diligence principles apply at scale.
Getting Started
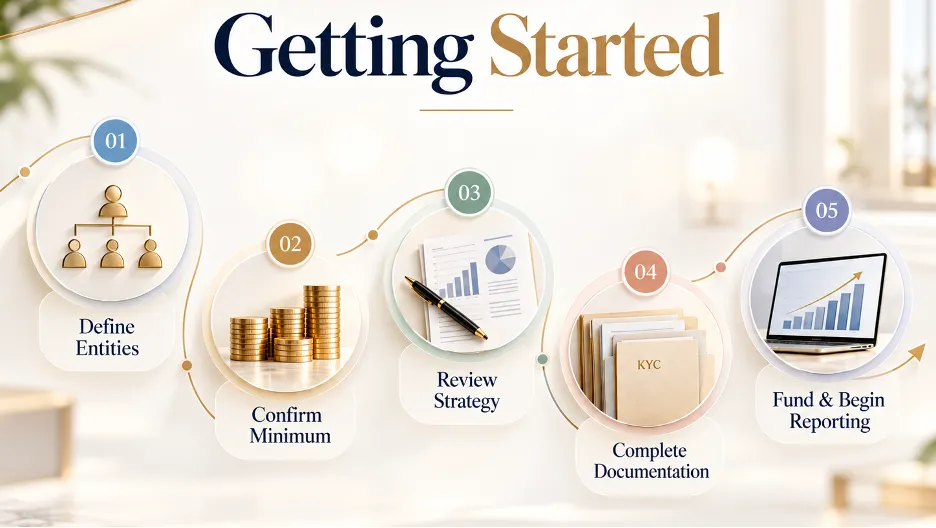
The process broadly follows the same sequence as for resident investors, with NRI-specific documentation layered in:
Define the entities involved, individual, HUF, trust, or corporate account — and how reporting should be structured across them.
Confirm the applicable minimum investment: ₹50 lakh for PMS, or the higher threshold applicable to AIF.
Review the strategy, fee structure, and SEBI registration with your investment committee or board.
Complete documentation specific to the entity type, alongside standard KYC.
Fund the account and begin regular, consolidated reporting cycles.
Ready to discuss a structure suited to your family office or corporate treasury?
Schedule a consultation with Chanakya Capital’s team.
Frequently Asked Questions
1. Can a family office invest across multiple entities with Chanakya Capital?
Yes, Family wealth rarely sits in one name, so allocations can be spread across individual accounts, family trusts, holding companies, or other entities, depending on what is available in your jurisdiction. Each account is reported in a consistent format, which makes it easier to see the whole family’s position in one view instead of piecing it together from separate statements.
2. What minimum investment applies to corporate investors?
Corporate accounts follow the same minimum ticket as individual investors, so there is no higher bar just because the investor is a company. The minimum is set by the regulator and can change over time, so confirm the current figure with the onboarding team before committing capital.
3. Which suits a multi-member family office better: a managed account or a pooled fund?
It comes down to how much customisation you need. A pooled fund keeps things simple, with one structure and one set of reports shared across members. Managed accounts let each entity hold its own portfolio, which helps when members have different goals, tax positions, or risk appetites. Families who value simplicity tend to prefer the pooled route, and those who value control tend to prefer separate accounts.
4. How does Chanakya Capital support board and trustee reporting?
You receive regular, transaction-level statements that can be consolidated into a single view for board meetings or trustee reviews. You also get direct access to the fund management team, so questions on performance, positioning, or strategy go to the people making the decisions rather than a service desk.
5. Do corporate and trust investors need extra documentation?
Yes. Entity accounts usually need more paperwork than individual ones, such as incorporation or trust documents, authorised signatory details, and ownership information, on top of standard identity checks. The exact list varies by entity type and country, and the onboarding team walks you through it step by step so nothing delays your start.
References
SEBI Investor Guidance — Portfolio Management Services: https://investor.sebi.gov.in/pms_final.html
Ministry of Corporate Affairs, Government of India: https://www.mca.gov.in