GIFT City isn’t tax-free. It offers a more favourable tax framework than domestic India under IFSCA rules, but if you’re an NRI tax resident in the US, UK, or Canada, you’re taxed on worldwide income at home. The India-side advantage reduces your Indian tax burden; it doesn’t touch what you owe your country of residence. Your actual liability depends on your residency, applicable DTAA provisions, and how your home jurisdiction classifies the fund’s income.
According to the investment team at Chanakya Capital, a SEBI-registered portfolio manager, “NRIs in the US or UK often assume GIFT City means zero tax it doesn’t. What it means is lower Indian-side tax and a cleaner structure. The home country tax question is separate and needs a local advisor, not a fund manager.”
Based in the US, UK or Canada and evaluating GIFT City as part of your India investment allocation?
What Is the Actual Tax Treatment Inside GIFT City for NRI Investors?
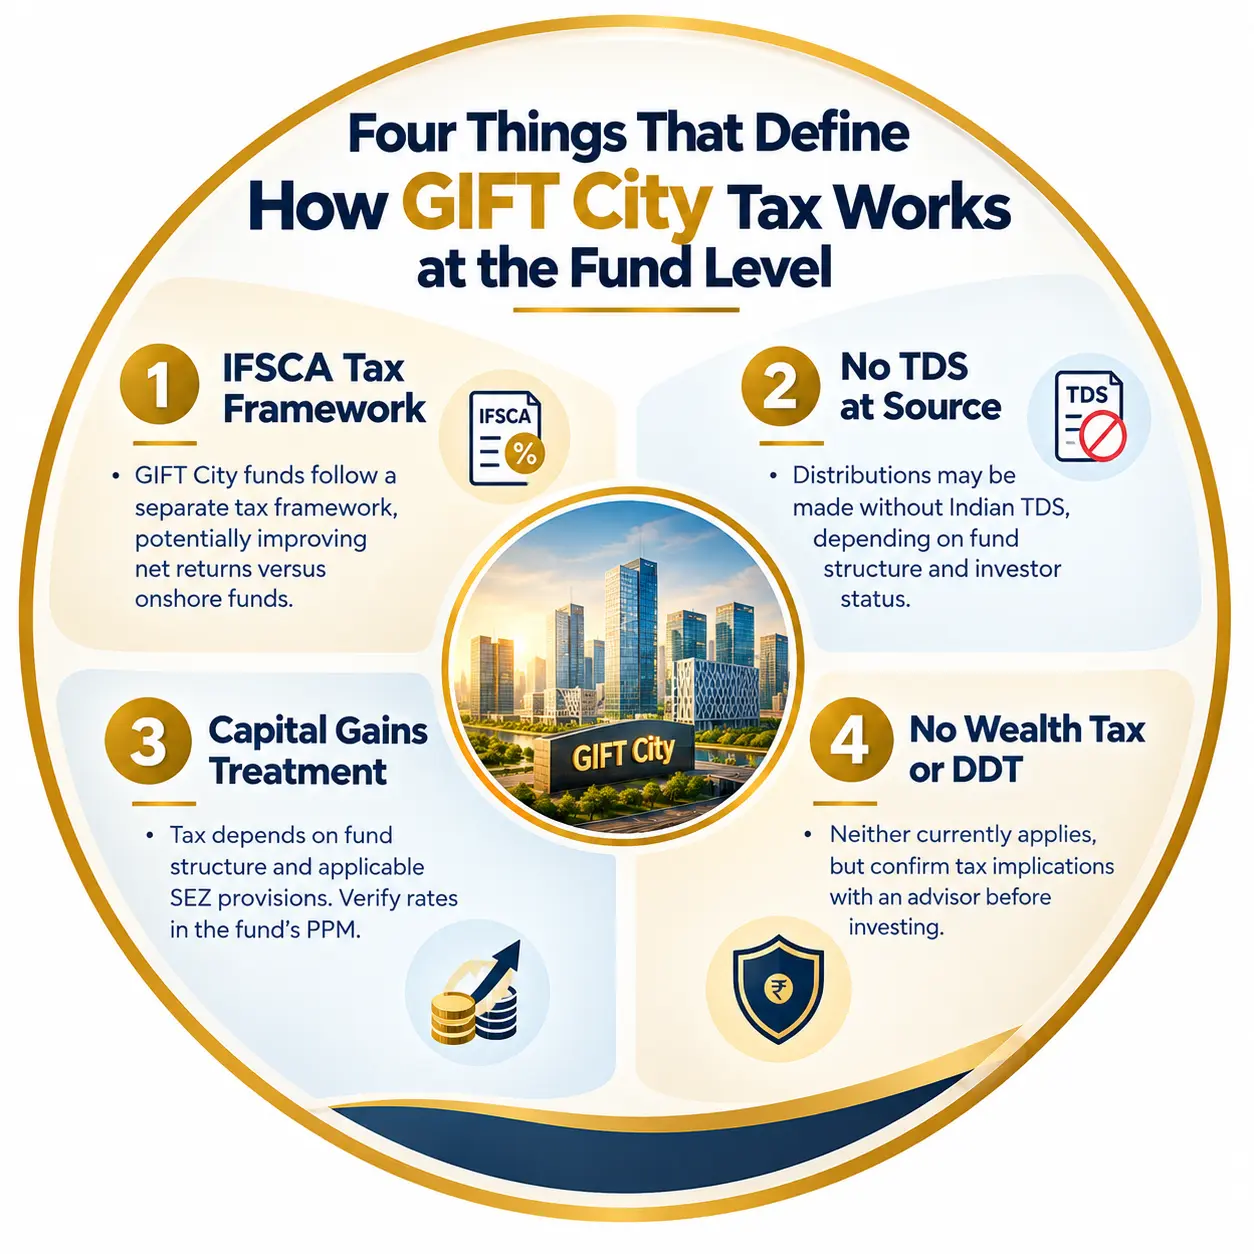
GIFT City’s tax advantage is real and material. Lower-tax structure, not a no-tax one and that distinction matters significantly for NRIs in high-tax home jurisdictions. Learn more about how Chanakya Capital’s GIFT City AIF is structured for NRI investors.
How Does Home Country Tax Work for NRIs in the US, UK and Canada?
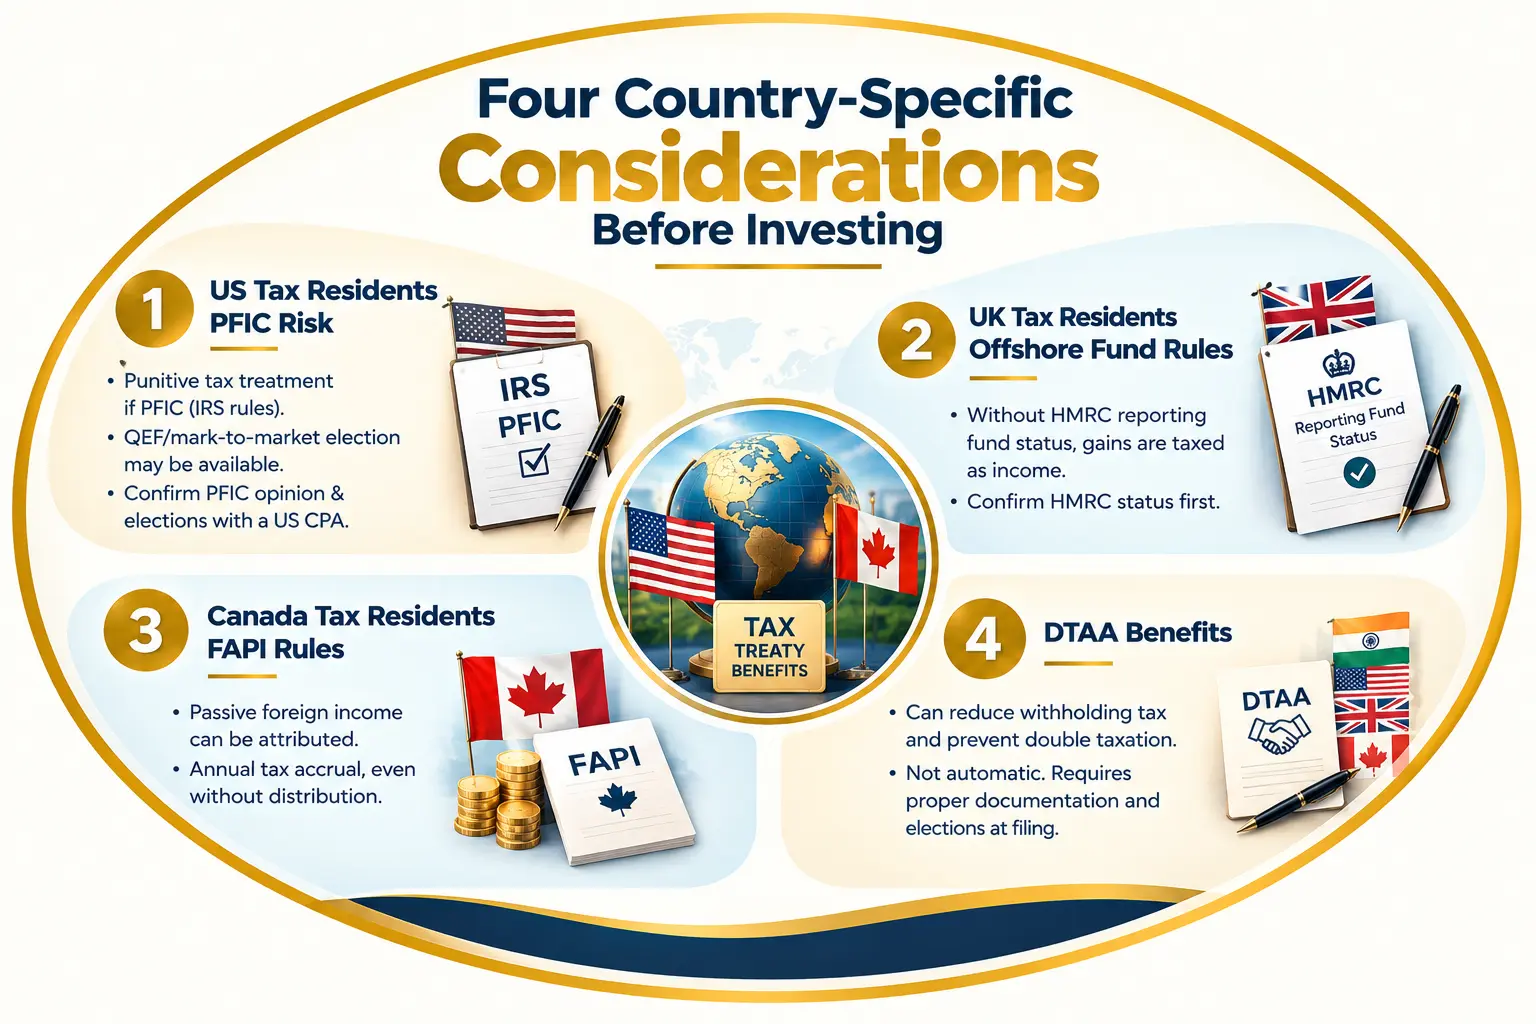
The India-side tax saving is genuine. But for NRIs in the US, UK, or Canada, home country tax can easily dwarf it, which is why a local tax specialist is non-negotiable before investing. For context beyond tax, GIFT City pros and cons for NRIs covers the full picture.
Why Choose Chanakya Capital?
Chanakya Capital Services Pvt. Ltd. is a SEBI-registered portfolio manager (INP000006040) and one of a select group of boutique managers approved to operate through GIFT City IFSC, managing concentrated Indian equity portfolios for NRIs in the US, UK, Canada, and across the Gulf through a USD-denominated Category III AIF. The firm provides full transparency on fund structure, IFSCA registration details, and PPM documentation that home country tax advisors need to assess treaty positions and PFIC or offshore fund classifications.
Chanakya doesn’t give home country tax advice and neither should your fund manager. What the firm does is make sure the fund structure is clean, the documentation is complete, and the investment process is good enough that the return justifies the tax complexity. A well-run GIFT City AIF with a disciplined process is worth navigating the tax paperwork.
FAQ
Frequently Asked Questions
Is GIFT City completely tax-free for NRIs?
No, GIFT City offers lower fund-level tax under IFSCA, but NRIs pay tax on global income in their home country regardless of where it’s earned.
Do US-resident NRIs face PFIC issues with GIFT City AIFs?
Potentially yes. US-resident NRIs must confirm PFIC classification and available elections with a US CPA before investing in any GIFT City fund.
Does India’s DTAA with the US, UK or Canada apply to GIFT City AIF returns?
DTAAs can reduce withholding tax, but treaty benefits aren’t automatic; proper documentation and treaty elections are required at the time of filing.
Is TDS deducted on GIFT City AIF returns for NRIs?
No, unlike onshore NRI PMS, GIFT City AIFs don’t apply the same TDS-at-source mechanism; returns are distributed net of fund-level tax.