

Yes, resident Indians can invest in GIFT City funds under LRS, up to USD 250,000 per person per financial year. FEMA treats GIFT City as a foreign jurisdiction, so money moving from your domestic account into a GIFT City AIF counts against your limit. In return, you get USD-denominated exposure, IFSCA regulation and international diversification without needing an offshore account. Check your LRS headroom, permitted investment categories and fund eligibility first.
According to the investment team at Chanakya Capital, a SEBI-registered portfolio manager, “most resident Indians don’t realise GIFT City is available to them they assume it’s an NRI-only structure. It isn’t, and the LRS route is cleaner than most offshore fund investments they’ve already considered.”
Looking to diversify beyond domestic Indian equity through a regulated IFSC structure?
How Does the LRS Route Into GIFT City Actually Work?
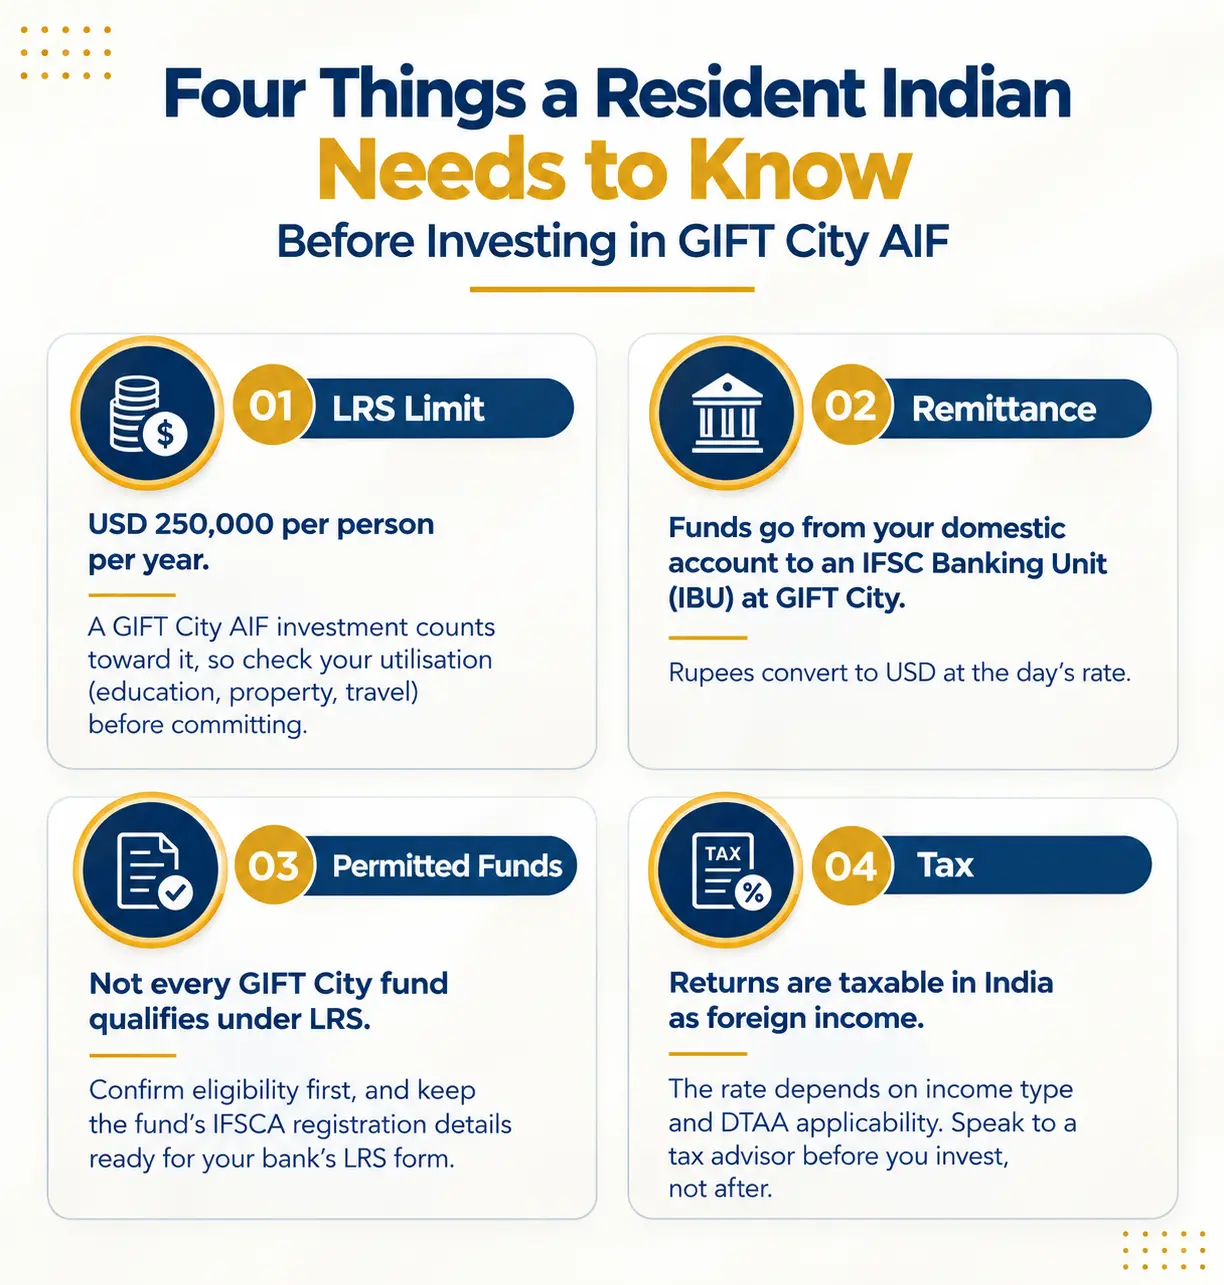
The LRS route is routine for major Indian banks. Paperwork is a one-time setup, and later investments into the same fund move faster. See who qualifies to invest with Chanakya Capital through GIFT City and onshore PMS.
What Are the Key Risks and Limits Resident Indians Should Know?

The constraints are real but manageable. Most resident Indians find the second investment significantly faster, since the compliance setup is already in place. For how your equity allocation fits the wider portfolio, see how HNIs split between PMS and AIF.
Why Choose Chanakya Capital?
Chanakya Capital Services Pvt. Ltd. is a SEBI-registered portfolio manager (INP000006040). One of a select group of boutique managers approved to operate through GIFT City IFSC. The firm serves resident Indians, NRIs, and foreign investors through onshore PMS and a USD-denominated Category III AIF. The GIFT City AIF is open-ended. No exit load. Same concentrated first-principles equity process as the onshore PMS. Accessible to resident Indians under LRS.
For resident Indians, the GIFT City AIF adds USD-denominated Indian equity exposure to a portfolio that’s otherwise entirely in rupees. No offshore account. No overseas broker. No FPI registration. The LRS remittance takes a few days. The fund does the rest.
FAQ
Frequently Asked Questions
Can resident Indians invest in GIFT City funds?
Yes, through RBI’s Liberalised Remittance Scheme up to USD 250,000 per individual per financial year.
Does a GIFT City AIF investment count against the LRS limit?
Yes, GIFT City is treated as a foreign jurisdiction under FEMA, so all remittances to IFSC funds count against the annual LRS ceiling.
What is the TCS rate on LRS remittances for GIFT City investments?
20% TCS applies on LRS remittances above ₹7 lakh per year it’s credited against income tax liability, not an additional tax.
Can both spouses invest separately in a GIFT City AIF under LRS?
Yes, each individual has a separate USD 250,000 LRS limit, effectively doubling the household’s annual investment capacity to USD 500,000.
