A turnaround investment is a bet on a business that has performed poorly but where underlying asset quality or management change creates recovery conditions the market hasn’t priced in yet. In India, where listed businesses are often cyclical and under-covered, turnarounds reprice violently when they do happen. The investor who identifies the inflection point before earnings recover captures the bulk of the return but that requires a framework that separates genuine recoveries from value traps.
According to the investment team at Chanakya Capital, a SEBI-registered portfolio manager, “the market prices a turnaround after two or three good quarters the investor who waits for confirmation has already missed 40% of the move; the one who acted on the operational signal six months earlier is sitting on a position the market is now racing to buy.”
Following a business through a difficult cycle and trying to identify whether the recovery is real?
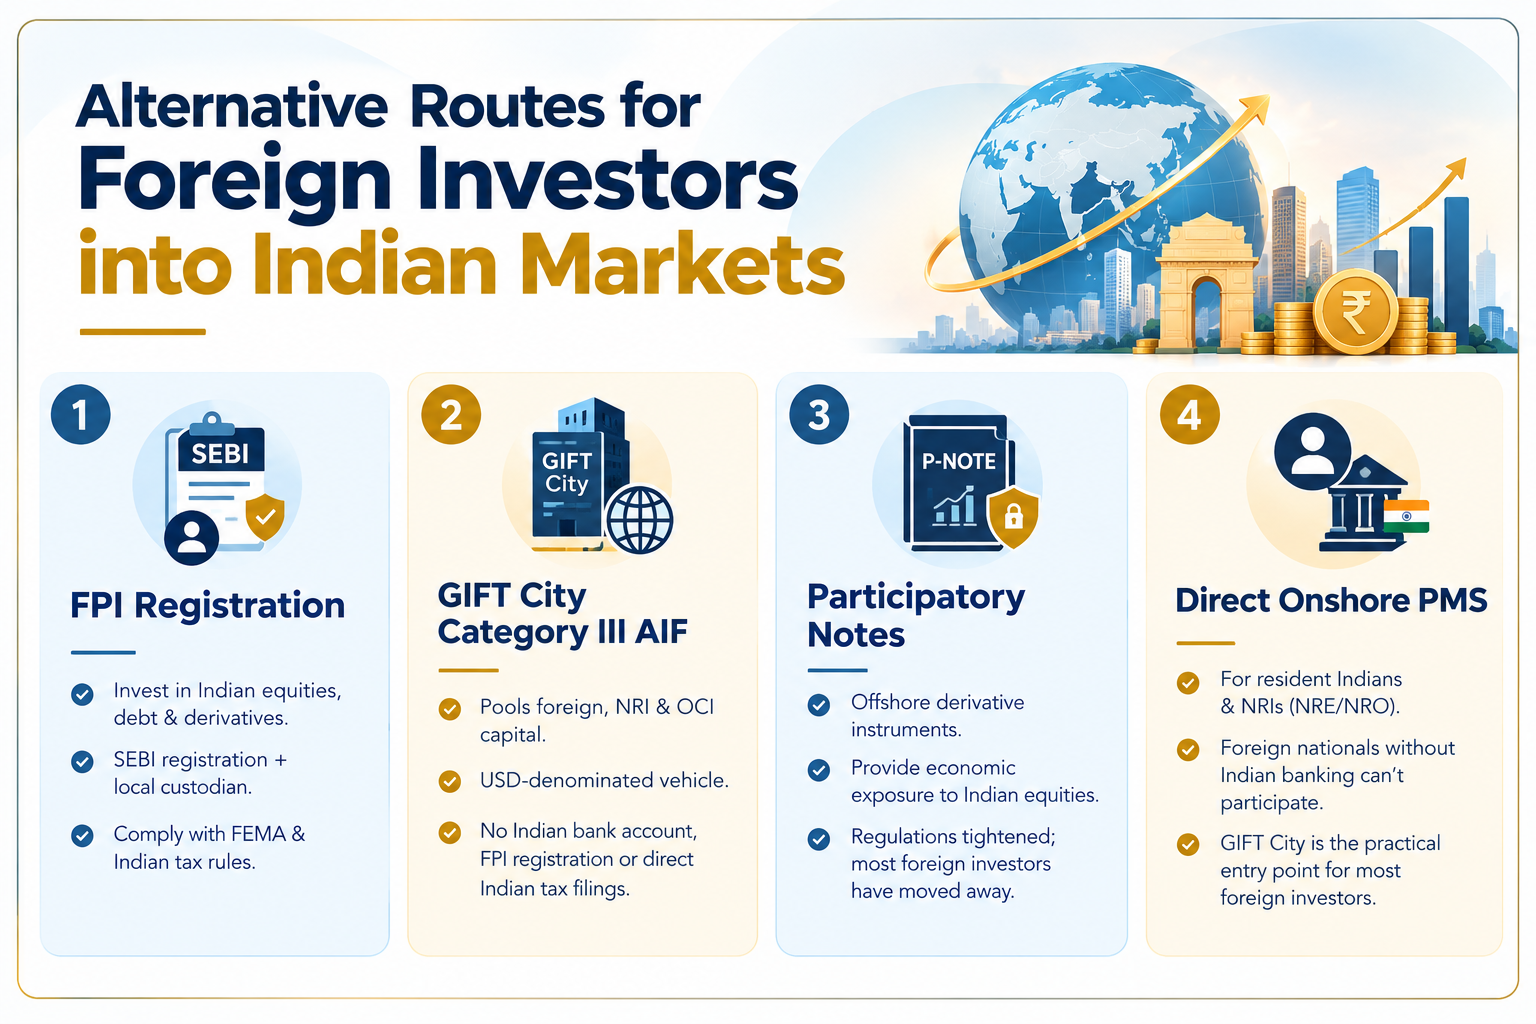
What Routes Are Available for Foreign Investors to Access Indian Equities?
None of these signals work in isolation. The edge is in reading all four together and acting before the consensus does. See how Chanakya Capital’s first-principles process identifies inflection points in Indian equities.
What Separates a Genuine Turnaround From a Value Trap?
Four questions that filter out businesses that look cheap but don’t recover:
- Is the core business structurally intact? A turnaround works when the model is sound, but execution was poor. Permanent disruption means cheap valuations reflect the new reality, not an opportunity.
- Does the promoter have skin in the game? A promoter who maintained their stake and communicated transparently through the bad years is a fundamentally different bet from one who cashed out at the top.
- Can the balance sheet survive the recovery timeline? Turnarounds take longer than expected. Investors who don’t model the balance sheet through the recovery often get diluted just before the business turns.
- Is there a catalyst or just hope? The market won’t reprice until something specific changes a debt restructuring, a contract win, a regulatory clearance. Hope is not a thesis.
Value traps look identical to turnarounds at the point of maximum pessimism. The difference is almost always in the balance sheet and the promoter and both require direct research. That’s what separates a boutique PMS from a large AMC running 60 stocks that structurally can’t do it.
Why Choose Chanakya Capital?
Chanakya Capital Services Pvt. Ltd. is a SEBI-registered portfolio manager (INP000006040) with 35+ years of combined Indian equity experience including direct exposure to 100+ business turnarounds across cycles 2008, 2013, 2018, and 2020. The investment process is built on first-principles business analysis: understanding the promoter, the balance sheet, the competitive position, and the catalyst before the market consensus forms. The portfolio runs 12 to 18 positions, and turnaround situations are sized with the same conviction as compounders not as speculative satellite positions.
Turnaround investing done well isn’t contrarian for the sake of it. It’s the discipline of buying a business that the market has given up on, at a price that reflects maximum pessimism, when the evidence says the recovery is already underway. That discipline requires patience, balance sheet literacy, and the willingness to hold a position that looks wrong for longer than most investors can stomach.
FAQ
Frequently Asked Questions
What is turnaround investing in simple terms?
Buying shares in a distressed company before the market prices in its recovery the return comes from the valuation re-rating as earnings improve.
How do you identify a turnaround stock early in India?
Look for management change, working capital normalisation, debt reduction, and a sector inflection ideally all four together before quarterly earnings reflect the recovery.
What is the difference between a turnaround and a value trap?
A turnaround has a structurally intact business, a credible promoter, balance sheet runway, and an identifiable catalyst a value trap has cheap valuations but no path to recovery.
How long does a turnaround investment take to play out in India?
Typically 18 months to 4 years from the point of maximum pessimism to full, market repricing; patience and balance sheet modelling are non-negotiable.